Personal finance education has become increasingly important in a world where financial decisions influence almost every aspect of everyday life. From managing monthly expenses and building emergency savings to understanding investments, credit scores, taxes, and retirement planning, individuals need practical financial knowledge to maintain long-term stability. However, traditional financial education does not always provide enough opportunities to understand real-world money management. Many people leave school without knowing how to prepare a realistic budget, compare financial products, manage debt, or develop responsible spending habits. As financial services become more digital, accessible, and complicated, the demand for convenient and understandable learning resources continues to grow.
Digital learning platforms are creating new opportunities to make financial education more engaging and accessible. Instead of depending entirely on textbooks or lengthy classroom sessions, learners can explore financial concepts through interactive explanations, practical examples, guided activities, and personalized learning experiences. The growing interest in AI-supported education also demonstrates how technology can help individuals understand complicated subjects at their own pace. In this changing environment, deepseekplay com represents an interesting keyword associated with the wider discussion about digital learning tools and their potential role in making personal finance knowledge easier to understand.
Why Personal Finance Education Needs a Modern Approach
Personal finance is not simply about earning money or reducing unnecessary expenses. It involves understanding how financial choices affect present circumstances and future opportunities. Someone who understands budgeting may be better prepared to manage irregular expenses, while someone familiar with credit management can make more informed borrowing decisions. Similarly, understanding investment fundamentals can help individuals evaluate long-term financial opportunities without depending entirely on advertisements or unverified advice.
Traditional financial education often focuses on theoretical explanations rather than practical decision-making. Students may learn the definitions of interest rates, inflation, savings, and investments without understanding how these concepts influence their daily lives. For example, knowing what compound interest means is useful, but calculating how regular savings can grow over several years makes the concept more meaningful. Modern education needs to connect financial theory with situations people actually encounter.
Another important challenge is that people have different financial backgrounds and learning requirements. A college student managing a limited monthly allowance needs different information from a working professional planning retirement or a small business owner managing irregular income. A flexible digital learning environment can help accommodate these differences by allowing individuals to explore relevant subjects according to their experience, financial goals, and available time.
How deepseekplay com Learning Tools Can Support Financial Literacy
The development of digital education has created opportunities to explain financial concepts in simpler and more practical ways. When learning resources combine structured information, interactive activities, and accessible explanations, individuals can gradually develop the confidence needed to make responsible financial decisions. deepseekplay com can be explored within this broader educational context as a keyword connected with technology-supported learning and the changing expectations of digital learners.
One of the biggest advantages of digital learning is convenience. People can study financial subjects without following a fixed classroom schedule. A beginner can spend time understanding the difference between saving and investing, while an experienced learner can explore more advanced subjects such as asset allocation, risk management, and retirement planning. This flexibility makes financial education more approachable for people with different schedules and responsibilities.
Digital learning resources can also make abstract financial topics easier to understand through examples. Consider someone who wants to purchase a smartphone using monthly installments. Understanding the total repayment amount, interest charges, processing fees, and payment duration can help that individual evaluate whether the purchase is financially sensible. Practical learning activities based on familiar situations can turn financial information into useful knowledge.
Making Budgeting Easier Through Interactive Learning
Budgeting is one of the most important foundations of personal financial management. It helps individuals understand where their money comes from, where it goes, and how much remains after essential expenses. Despite its importance, many people find budgeting difficult because they do not have a clear system for tracking income and spending. Digital educational tools can help simplify this process by explaining budgeting methods and demonstrating how different financial choices influence monthly balances.
For example, a learner earning a fixed monthly salary can create a sample budget covering rent, groceries, transportation, utility bills, savings, and entertainment. By changing the amount assigned to each category, the learner can observe how spending decisions affect the remaining balance. This approach makes financial planning more practical than simply memorizing budgeting definitions.
The 50/30/20 budgeting method is another useful concept for beginners. It generally suggests allocating 50% of income to needs, 30% to wants, and 20% to savings and debt repayment. However, these percentages are guidelines rather than universal rules. Someone living in an expensive city may need to allocate more toward essential expenses, while another individual may be able to save a larger percentage.
Learning environments associated with deepseekplay com can be discussed as part of the wider movement toward accessible educational experiences that help learners explore budgeting concepts, compare financial scenarios, and develop better spending habits. The most valuable learning experience is one that encourages individuals to apply these principles to their own circumstances instead of treating a sample budget as a fixed financial formula.
Understanding Saving Habits and Emergency Funds
Saving money is an essential financial habit, but it requires consistency and realistic planning. Many individuals postpone saving because they believe they need a large income before setting aside money. In reality, developing a regular saving habit can begin with relatively small contributions. The important factor is creating a manageable routine that can continue over time.
Emergency funds are particularly important because unexpected expenses can arise without warning. Medical bills, vehicle repairs, temporary unemployment, and urgent household expenses can create financial pressure. Without savings, individuals may depend on credit cards or expensive borrowing options to manage these situations. Financial education should therefore explain why emergency savings matter and how people can gradually build a reserve.
A common recommendation is to work toward an emergency fund covering three to six months of essential living expenses. However, the appropriate amount depends on employment stability, household responsibilities, income patterns, and personal circumstances. Someone with irregular income may require a larger financial cushion than someone with a predictable salary.
Interactive learning can demonstrate how regular contributions accumulate over time. For instance, saving a fixed amount every month allows learners to see how consistency creates progress even when individual contributions appear small. Such examples encourage realistic financial expectations and help people understand that financial security is generally developed through repeated decisions rather than one major achievement.
Learning About Credit Scores, Loans, and Debt Management
Credit management is another major area of personal finance education. Credit cards, personal loans, education loans, and home loans are common financial products, but many consumers do not fully understand their costs and responsibilities. Borrowing can provide access to important opportunities, yet poorly managed debt can create long-term financial difficulties.
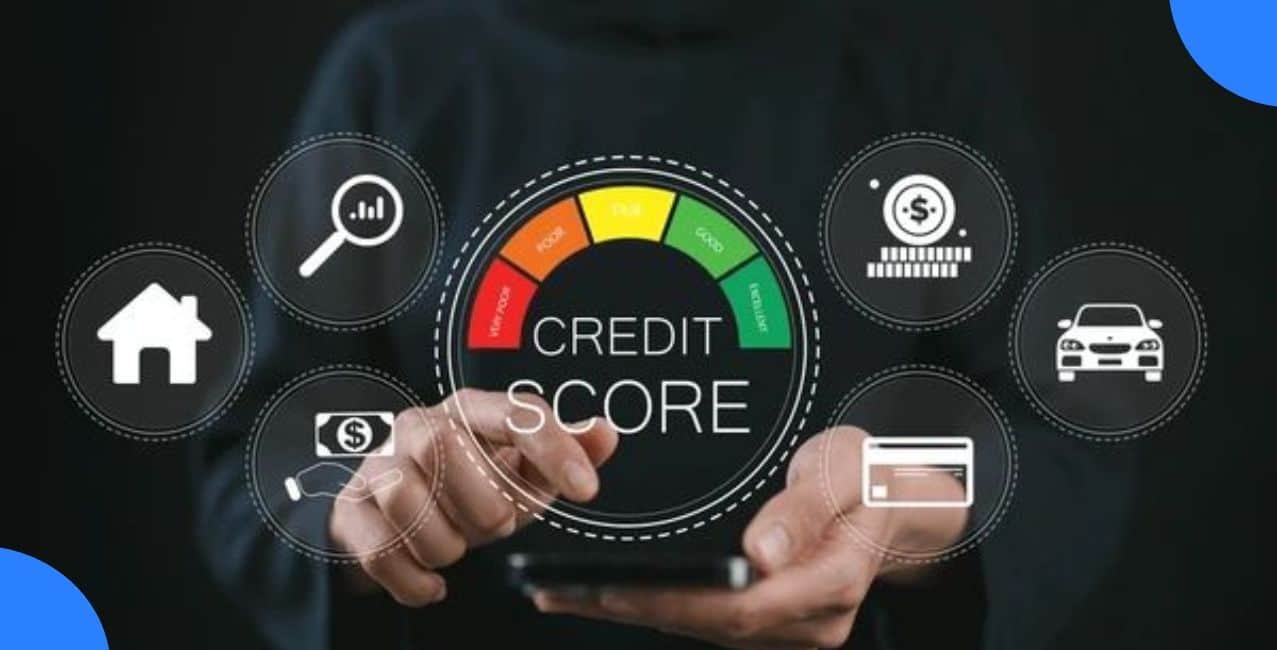
A credit score is one factor lenders may consider when evaluating an individual’s creditworthiness. Payment history, credit utilization, length of credit history, credit mix, and recent credit applications can influence credit assessments, depending on the scoring system. Understanding these factors helps consumers recognize why responsible borrowing and timely repayments are important.
Educational resources can explain the difference between secured and unsecured loans, fixed and variable interest rates, and minimum payments versus full repayments. These distinctions become especially valuable when someone compares multiple borrowing options. For example, a credit card offering attractive rewards may still become expensive if the outstanding balance is not paid within the applicable interest-free period.
debt management education should also explain the importance of calculating total borrowing costs instead of focusing only on monthly installments. A lower monthly payment may involve a longer repayment period and a higher overall cost. Learning through practical examples can help individuals identify these differences before making financial commitments.
Exploring Investment Basics Without Unnecessary Complexity
Investment education is becoming increasingly relevant as more people explore opportunities to grow their wealth. However, entering financial markets without understanding basic principles can expose beginners to unnecessary risks. A strong educational foundation should explain the relationship between potential returns, investment duration, market fluctuations, and individual risk tolerance.
Beginners should first understand the differences between savings accounts, fixed deposits, bonds, mutual funds, exchange-traded funds, and individual stocks. Each financial instrument has different characteristics, costs, liquidity considerations, and risk levels. Understanding these differences helps learners avoid assuming that every investment offers guaranteed growth.
Diversification is another important concept. It involves spreading investments across different assets rather than depending entirely on one company, industry, or investment category. Diversification cannot eliminate market risk, but it may help reduce the impact of poor performance in a particular investment.
Digital educational resources can make these subjects easier to approach through hypothetical investment scenarios. Learners can examine how different asset allocations might respond to changing market conditions without immediately risking real money. deepseekplay com fits into the broader conversation about accessible digital learning, where complicated financial subjects can be introduced through understandable explanations and structured educational activities.
The Role of AI in Modern Financial Education
Artificial intelligence is changing the way people access information, practice new skills, and understand complicated subjects. In education, AI-powered systems can help explain unfamiliar terminology, organize learning materials, generate practice questions, and provide additional examples when a learner struggles with a particular concept.
Personal finance is particularly suitable for this type of educational assistance because many financial subjects involve calculations and comparisons. A learner might ask for an explanation of annual interest, request a sample monthly budget, or explore how inflation affects purchasing power. An AI-supported learning environment can help break these topics into smaller steps, making the learning process less intimidating.
However, AI-generated financial information must be evaluated carefully. Educational explanations are not automatically accurate, and financial rules can differ according to location, regulations, product conditions, and individual circumstances. Learners should verify important information through reliable financial institutions, official government resources, and qualified professionals when necessary.
The growing interest in deepseekplay com also highlights the importance of discussing digital platforms in relation to accessible knowledge and technology-supported learning. The value of any educational tool ultimately depends on the accuracy of its information, transparency about its capabilities, and usefulness in helping people develop independent financial judgment.
Important Personal Finance Topics Learners Should Understand
A comprehensive financial education program should cover more than budgeting and savings. Individuals need a broad understanding of how different financial decisions connect with one another. The following subjects provide a useful foundation for beginners:
- Income management: Understanding salary, additional income, taxes, and regular financial obligations.
- Financial planning: Setting short-term and long-term goals based on realistic income and expenses.
- Debt awareness: Comparing borrowing costs, repayment schedules, and the consequences of missed payments.
- Investment fundamentals: Learning about diversification, market risk, investment duration, and potential returns.
- Financial security: Understanding emergency funds, insurance, and retirement preparation.
These subjects create a foundation that learners can expand as their financial responsibilities increase. The objective is not to become an expert in every financial product but to develop enough knowledge to recognize opportunities, understand risks, and ask informed questions.
Comparing Traditional and Digital Personal Finance Education
Traditional education and digital learning both contribute to financial literacy, but they offer different advantages. Classroom-based learning provides structured instruction, direct interaction with teachers, and opportunities for group discussions. Digital learning provides flexibility, convenient access, and opportunities to revisit difficult concepts whenever necessary.
| Learning factor | Traditional education | Digital learning |
|---|---|---|
| Accessibility | Usually follows a fixed schedule | Often available at flexible times |
| Learning pace | May follow a common classroom speed | Can support individual learning speeds |
| Practical examples | Depends on teaching methods | Can include interactive scenarios |
| Personalization | Limited in larger groups | May offer adaptable learning experiences |
| Revision | Depends on available materials | Lessons can often be revisited |
Neither approach needs to replace the other. A combination of classroom instruction, practical exercises, reliable digital resources, and independent research can provide a stronger educational experience. Financial literacy develops most effectively when learners have opportunities to understand concepts and apply them to realistic situations.
How Students and Young Professionals Can Benefit
Students are among the groups that can benefit significantly from early personal finance education. Many young adults begin managing money independently when they enter college, start working, or move away from their families. Without basic financial knowledge, they may struggle with everyday decisions involving accommodation, transportation, food expenses, education costs, and credit products.
Introducing financial education at an early stage can help students recognize the difference between essential and discretionary spending. They can also learn why saving regularly matters, how digital payment systems work, and why sharing financial information with unknown parties creates security risks. These lessons can build responsible habits before individuals begin managing larger financial commitments.
Young professionals face another set of challenges. Their priorities may include paying education loans, supporting family members, building savings, purchasing insurance, and planning for future investments. Learning tools connected with deepseekplay com can be considered within the broader discussion of how digital education may make financial concepts more approachable for people entering these new stages of life.
The most useful approach is to connect education with personal circumstances. A student can begin with a simple monthly spending plan, while a working professional may explore retirement contributions and long-term financial goals. Gradually increasing the complexity of financial learning helps individuals develop confidence without feeling overwhelmed.
Building Better Financial Decisions Through Real-Life Scenarios
Financial education becomes more effective when learners can examine realistic situations. Instead of studying concepts separately, they can explore how multiple financial decisions influence one another. For example, someone planning to purchase a vehicle should consider the purchase price, loan interest, insurance, fuel, maintenance, and regular household expenses. Looking at the complete financial picture can prevent decisions based only on an attractive monthly installment.
Another useful scenario involves managing an unexpected reduction in income. Learners can explore which expenses should receive priority, how emergency savings can help, and why taking additional debt may create complications. These exercises develop problem-solving abilities and encourage people to prepare for uncertainty.
Scenario-based learning also helps individuals recognize that financial decisions are rarely identical for everyone. A strategy that works for one household may not suit another because of differences in income, location, responsibilities, and financial goals. Educational platforms should therefore encourage critical thinking instead of presenting a single financial method as suitable for every learner.
Privacy and Security in Digital Financial Learning
As financial education moves toward online platforms, privacy and cybersecurity become increasingly important. Learners may use digital tools to organize budgets, study financial documents, or explore hypothetical money-management situations. They should understand how personal information is handled before entering sensitive details into any online service.
One essential principle is to avoid sharing confidential information unnecessarily. Banking passwords, one-time passwords, complete payment card details, and account authentication credentials should never be entered into an ordinary educational chatbot or unverified learning platform. Even when a service appears convenient, users should review its privacy policies and security practices.
Financial literacy should also include awareness of online scams, phishing messages, fake investment opportunities, and misleading financial advertisements. Understanding how these threats operate can help individuals protect their money and personal information. Digital education is most beneficial when it develops both financial knowledge and responsible online behavior.
Challenges in Adopting Digital Finance Education
Although digital learning provides several advantages, it also has limitations. Not everyone has reliable internet access, suitable devices, or sufficient digital skills to use online educational resources effectively. Language differences and complicated financial terminology can create additional barriers, especially for people who are new to formal financial education.
Another challenge is the large amount of financial information available online. Different websites, social media creators, and automated tools may provide conflicting explanations. Some resources may also promote financial products without explaining their risks or commercial interests. Learners need to develop the ability to evaluate information rather than accepting every recommendation as trustworthy.
There is also a difference between understanding a financial concept and making an appropriate financial decision. Someone may understand how stock markets operate but still lack the experience required to evaluate a particular investment. Digital learning should therefore complement independent research and professional guidance instead of replacing them.
The Future of Personal Finance Education
The future of personal finance education is likely to become more flexible, interactive, and accessible. AI-supported explanations, mobile learning environments, practical simulations, and personalized educational pathways may help more people understand financial subjects. These developments can make learning more convenient for students, professionals, families, and individuals who previously had limited access to structured financial education.
Another important development is the growing need for financial education that reflects changing economic conditions. Inflation, digital payments, online banking, changing employment patterns, cybersecurity threats, and new investment products continue to influence financial decisions. Educational content must evolve alongside these developments so learners can understand current challenges rather than relying exclusively on outdated examples.
In this environment, deepseekplay com can be positioned as part of the wider discussion about technology-driven learning and its potential contribution to financial awareness. The long-term success of digital financial education will depend on reliable information, practical learning opportunities, transparent technology, and a strong emphasis on independent decision-making.
Conclusion
Personal finance education is an essential life skill that helps individuals manage income, control expenses, build savings, understand debt, and prepare for future financial responsibilities. As technology continues to change how people access information, digital learning tools are creating new opportunities to make these subjects easier to understand. Interactive explanations, realistic examples, flexible learning experiences, and AI-supported educational assistance can help learners develop stronger financial awareness at their own pace.
The growing conversation around deepseekplay com reflects the wider interest in making educational experiences more accessible through digital technology. However, successful financial education requires more than convenient tools. Learners must also develop critical thinking, verify important information, understand financial risks, and apply knowledge according to their individual circumstances. By combining trustworthy educational resources with consistent learning and practical experience, individuals can build healthier financial habits and make more confident decisions throughout their lives.

.jpg&description=Discover how deepseekplay com learning tools can transform personal finance education through interactive learning, budgeting knowledge, and smarter financial decisions.)